One of the biggest myths in real estate?
“You need 20% down to buy a home.”
That’s not always true.
While a 20% down payment has advantages, many buyers — especially first-time homebuyers — purchase homes with far less. According to the National Association of Realtors (NAR), the median down payment for first-time buyers in recent years has typically ranged between 6%–8%, not 20%.
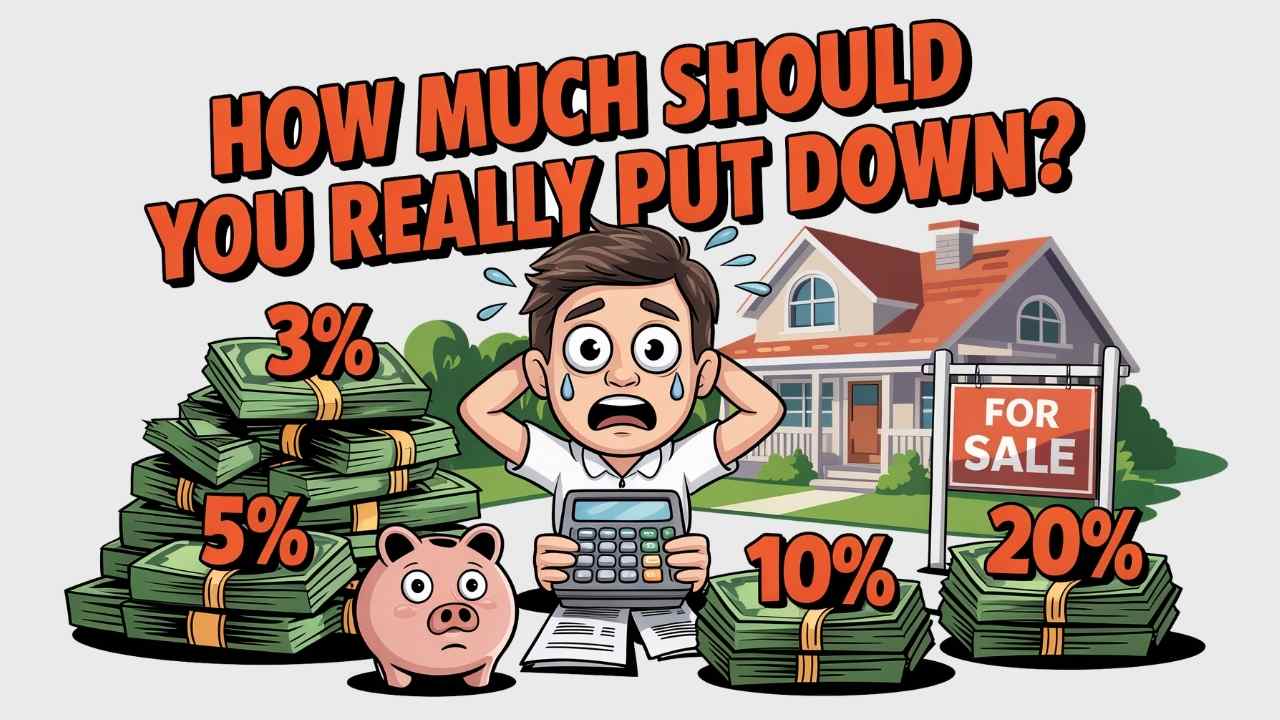
So what’s the right number for you — 3%, 5%, 10%, or 20%?
Let’s break it down clearly and practically.
💰 3% Down: The Minimum Entry Point
This option is common for first-time buyers using conventional programs like those backed by Fannie Mae (HomeReady®) or Freddie Mac (Home Possible®).
Pros:
-
Lower upfront cash requirement
-
Lets you buy sooner
-
Preserves savings for emergencies
Cons:
-
Higher monthly mortgage payment
-
Requires Private Mortgage Insurance (PMI)
-
Less equity at the start
👉 Example:
On a $300,000 home, 3% down is $9,000.
This can be ideal if:
-
You have stable income
-
You don’t want to drain your savings
-
You expect income growth
💰 5% Down: A Balanced Approach
This is one of the most common conventional down payments.
Pros:
-
Slightly lower monthly payment than 3%
-
Builds equity faster
-
Still relatively accessible
Cons:
-
PMI is still required
-
Higher upfront cash than 3%
👉 Example:
5% down on a $300,000 home = $15,000.
This option works well if:
-
You have moderate savings
-
You want better loan terms than the minimum
-
You plan to stay in the home long enough to build equity
💰 10% Down: Lower Risk, Lower PMI
At 10%, you’re in a stronger equity position from day one.
Pros:
-
Reduced PMI cost
-
Lower monthly payment
-
Better interest rate potential
Cons:
-
Requires significant savings
-
Cash tied up in home equity
👉 Example:
10% down on a $300,000 home = $30,000.
This may make sense if:
-
You have strong savings
-
You want to reduce long-term borrowing costs
-
You’re risk-averse about monthly obligations
💰 20% Down: The Traditional Benchmark
Putting 20% down eliminates PMI on conventional loans.
Pros:
-
No PMI
-
Lower monthly payment
-
Strong equity position
-
More competitive offer in some markets
Cons:
-
Large upfront cash requirement
-
Opportunity cost (money tied up vs. investing elsewhere)
👉 Example:
20% down on a $300,000 home = $60,000.
According to Consumer Financial Protection Bureau (CFPB), avoiding PMI can significantly reduce monthly payments over time — but it doesn’t automatically mean it’s the smartest financial move in every situation.
📊 What Do Most Buyers Actually Do?
Data from the National Association of Realtors shows:
-
First-time buyers: often under 10%
-
Repeat buyers: typically closer to 15–20%
-
FHA loans (insured by the Federal Housing Administration): allow as little as 3.5% down
So no — 20% is not the universal rule.
🤔 So What’s “Best” for You?
There is no one-size-fits-all answer. The best down payment depends on:
-
Your emergency fund (ideally 3–6 months of expenses)
-
Your monthly comfort level
-
Your long-term plans for the property
-
Current interest rates
-
Investment opportunities elsewhere
-
Job stability and income trajectory
Sometimes it’s smarter to put 5% down and keep liquidity.
Sometimes 20% down provides peace of mind.
This is less about “what’s standard” and more about what’s sustainable for you.
💡 A Simple Rule of Thumb
Before choosing your down payment, ask:
-
Will I still have a strong emergency fund after closing?
-
Am I comfortable with the projected monthly payment?
-
Am I buying within my true budget — not my maximum approval?
If you can answer yes to all three, you’re likely in a good position.
Final Thoughts
The right down payment isn’t about impressing a lender — it’s about protecting your financial stability while stepping into homeownership wisely.
Buying a home should feel exciting, not financially suffocating.
Disclaimer
This article is for informational and educational purposes only and should not be considered financial, legal, or lending advice. Loan programs, eligibility requirements, interest rates, and mortgage insurance rules may vary by lender, borrower profile, and location and are subject to change. Always consult with a licensed mortgage professional, financial advisor, or real estate professional before making any financial decisions related to purchasing real estate.
Download these helpful checklists to guide you through your buying and selling journey.
Home Buyer’s Checklist
Home Seller’s Checklist
Mistakes To Avoid
10 Body Changes After 60 Worth Discussing With Your Doctor
Download these helpful checklists to guide you through your buying and selling journey.Home Buyer's ChecklistHome Seller's ChecklistMistakes To Avoid
Morning Headaches in Seniors: 9 Causes, Warning Signs and What to Do
Download these helpful checklists to guide you through your buying and selling journey.Home Buyer's ChecklistHome Seller's ChecklistMistakes To Avoid
Sudden Weight Gain From Fluid Retention: Causes, Warning Signs & What to Do
Download these helpful checklists to guide you through your buying and selling journey.Home Buyer's ChecklistHome Seller's ChecklistMistakes To Avoid